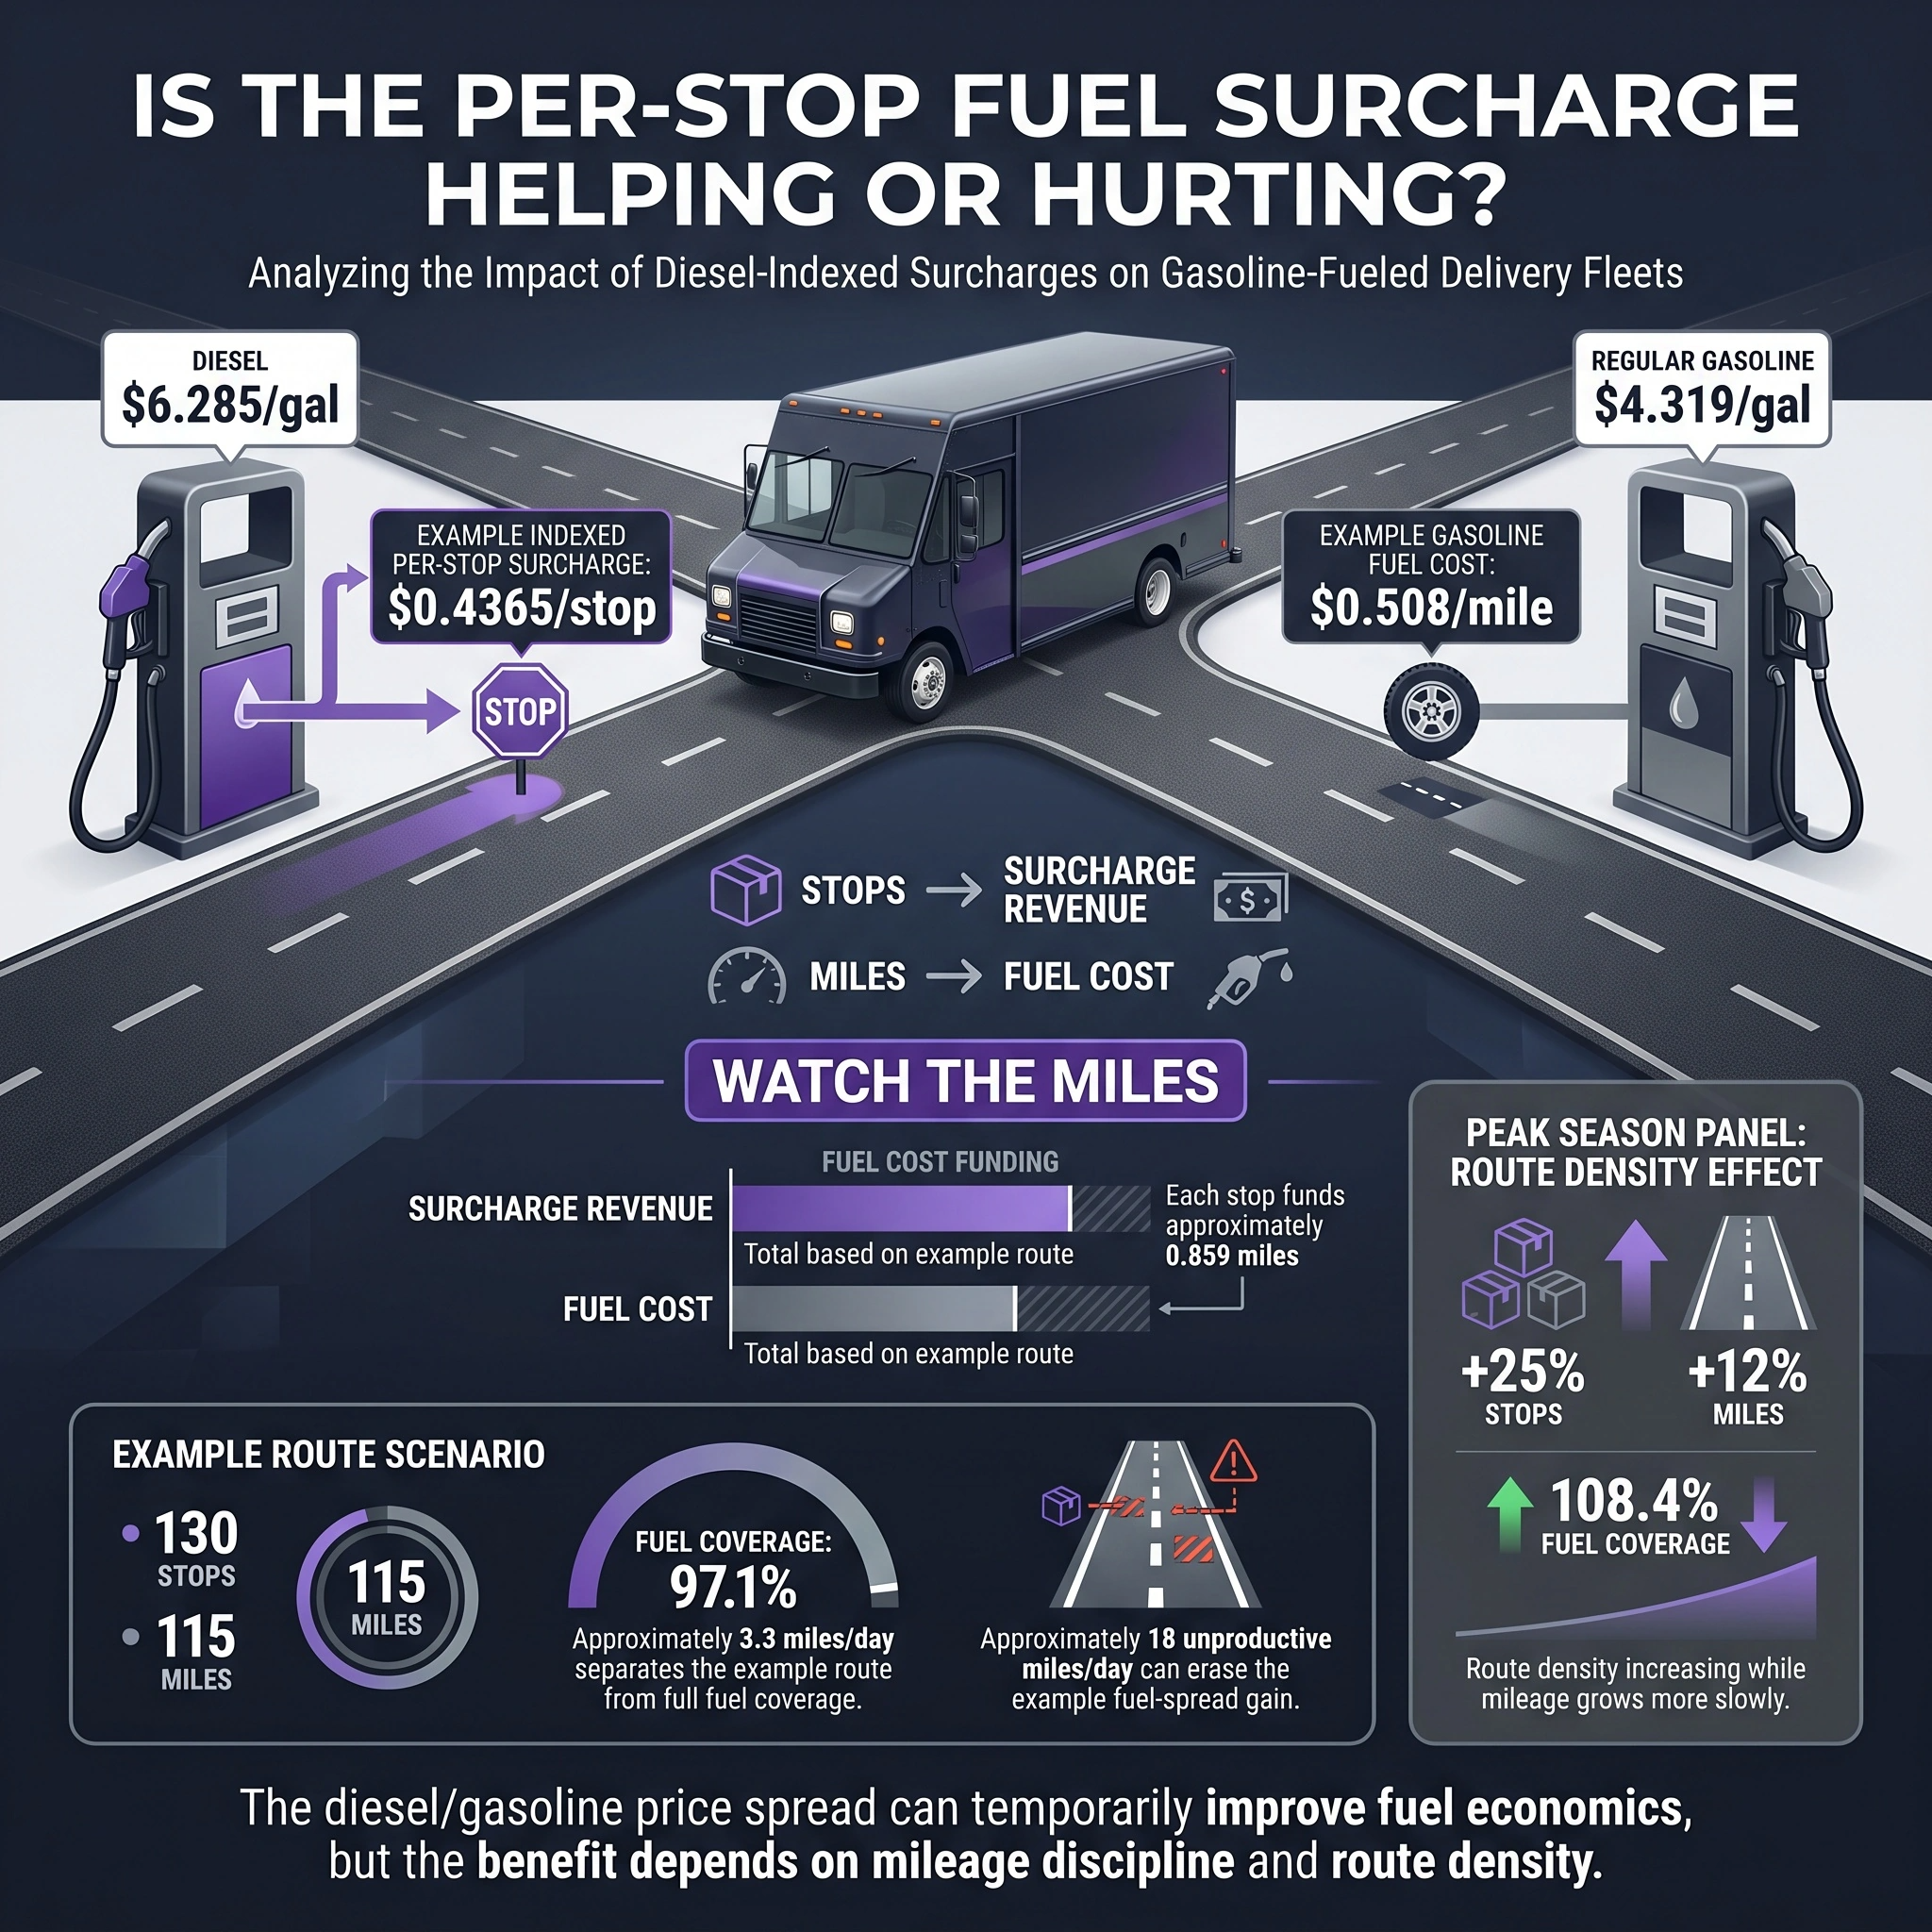
Your contract indexes your Per-Stop Fuel Surcharge to the weekly average self-service cash price per gallon of diesel fuel for your station's ZIP code. Every ISP Agreement uses that language. FedEx does not write a separate index for contractors running gasoline vehicles, and it does not negotiate the indexing fuel based on what is actually in your fleet.
Most CSPs run gasoline. Step vans, Transits, ProMasters, E-series — the majority of P&D fleets in this network burn regular unleaded. Which means the majority of contractors are being paid a fuel surcharge that tracks a fuel they do not buy. In most years that is a footnote, because gas and diesel move roughly together. This is not most years.
Diesel averaged $6.285 a gallon the week of September 14, 2026 — the highest weekly price the U.S. Energy Information Administration has ever recorded and the first time it has ever crossed $6, driven by tight distillate supply rather than a crude shortage. That is up more than 37% from the July low. Regular gasoline over the same stretch went from about $3.78 to $4.319 — up roughly 14% (EIA September 15 fuel update). Diesel is up $2.55 a gallon year over year; gas is up $1.15.
So, the answer to whether the surcharge is helping or hurting is, for most of you, genuinely good news: it is helping, by more than you probably realize, and it is temporary. But the money only reaches your bottom line if you control the one variable the surcharge does not pay for. This post covers how much the spread is worth on a real CSA, why every mile matters more now than it did in June, and the specific numbers to manage against before peak volume lands on November 21.